Would Your Portfolio Pass the Ultimate Stress Test?
RPMEX “Ounces of Perspective”
A 26-year comparison of physical gold and the S&P 500 asks a different question: not simply which investment finished ahead, but what might remain resilient if the market balloon meets gravity.
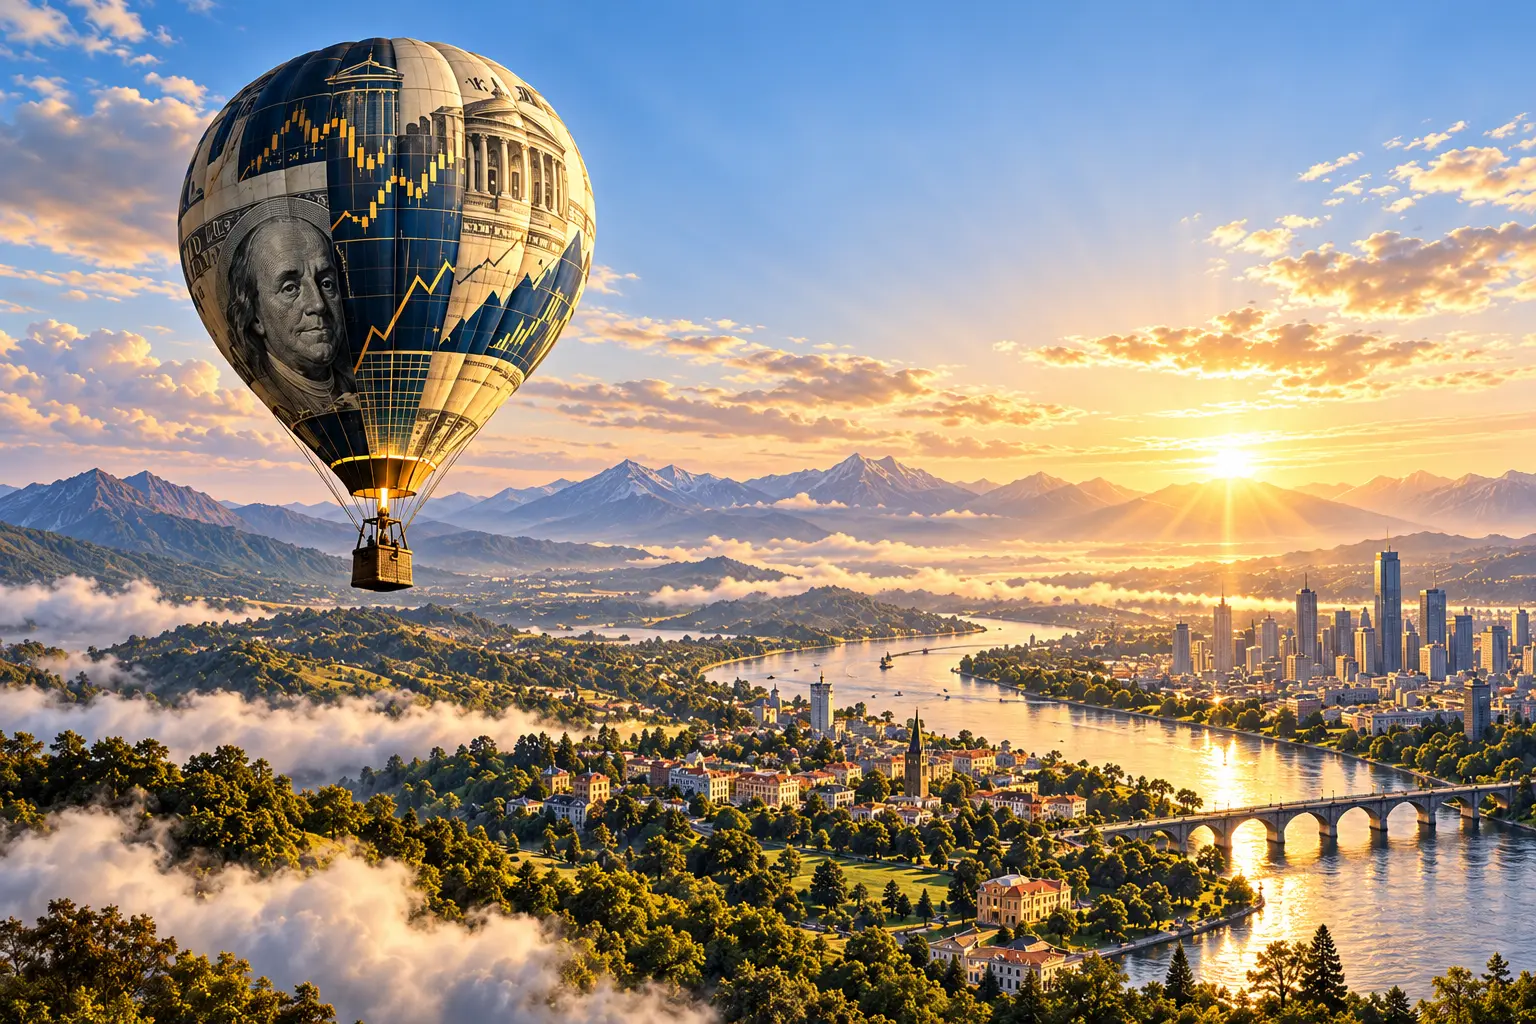
For years, the average investor has ridden higher in what might be called a market hot-air balloon. Rising stock prices, expanding valuations and easy access to credit have created the comforting impression that altitude equals safety.
Financial bubbles can grow larger and remain aloft longer than almost anyone expects. Their timing is impossible to predict, but their ending is not: every bubble eventually meets gravity. Some deflate gradually. Others burst. The important question is not whether anyone can identify the precise moment—it is whether a portfolio is prepared for the descent.
Less Than a Century Ago
The Great Depression is not ancient history. It began less than a century ago, and the experiences of its institutions, businesses and families remain well documented.
Before the collapse, the stock market appeared nearly unstoppable. The Dow Jones Industrial Average increased approximately sixfold between 1921 and its September 1929 peak. Rising prices encouraged confidence, confidence attracted more money, and the market’s success increasingly became its own justification.
Then the cycle turned. From its September 1929 peak to its July 1932 low, the Dow lost approximately 89% of its value. Banks failed, credit contracted, unemployment surged and years of monetary and economic havoc followed. Investors who believed recent performance had eliminated risk discovered that prosperity, liquidity and confidence can reverse together.
History does not repeat in precisely the same form, but financial cycles are well documented. Credit expands and contracts. Valuations rise and fall. Fear replaces greed, often more quickly than greed replaced caution. The names, technologies and policies change; human behavior remains remarkably consistent.
What the Actual Comparison Shows
To move beyond slogans, we compared two disciplined investors. Each invested $100 every Friday from January 7, 2000 through August 28, 2026. One accumulated physical gold. The other accumulated SPY, an exchange-traded fund designed to track the S&P 500, with dividends reinvested.
The physical-gold model assumed a 5% acquisition premium and a liquidation value 2% below spot. Total contributions were $139,100.
| Strategy | Modeled value on August 31, 2026 |
|---|---|
| SPY with dividends reinvested | $852,537 |
| Gold valued at spot | $785,751 |
| Physical-gold liquidation value | $733,367 |
Illustrative historical model using weekly closes. It does not include taxes, storage, account fees or differences in retirement-account tax treatment. Past performance does not guarantee future results.
The stock-market investment finished ahead. That fact should not be hidden; it is central to the discussion. Equities represent ownership in productive businesses and have historically played an important role in long-term wealth creation.
But ending value is not the only measure of portfolio strength. The more difficult question is what happens when the conditions that supported the winning investment change.
Apply the Stress
The Dow’s 1929–1932 decline does not forecast what will happen next, and applying it to a modern portfolio is a hypothetical exercise—not a prediction. It does, however, show how dramatically a long period of apparent outperformance can be altered by a severe drawdown.
| Hypothetical stress | Resulting modeled value |
|---|---|
| SPY portfolio after an 89% decline | $93,779 |
| Physical gold after a 20% decline | $586,694 |
| Physical gold with no price change | $733,367 |
These are simple scenario calculations, not forecasts. Gold can decline during liquidity events, and there is no assurance that it would retain its value during any particular crisis.
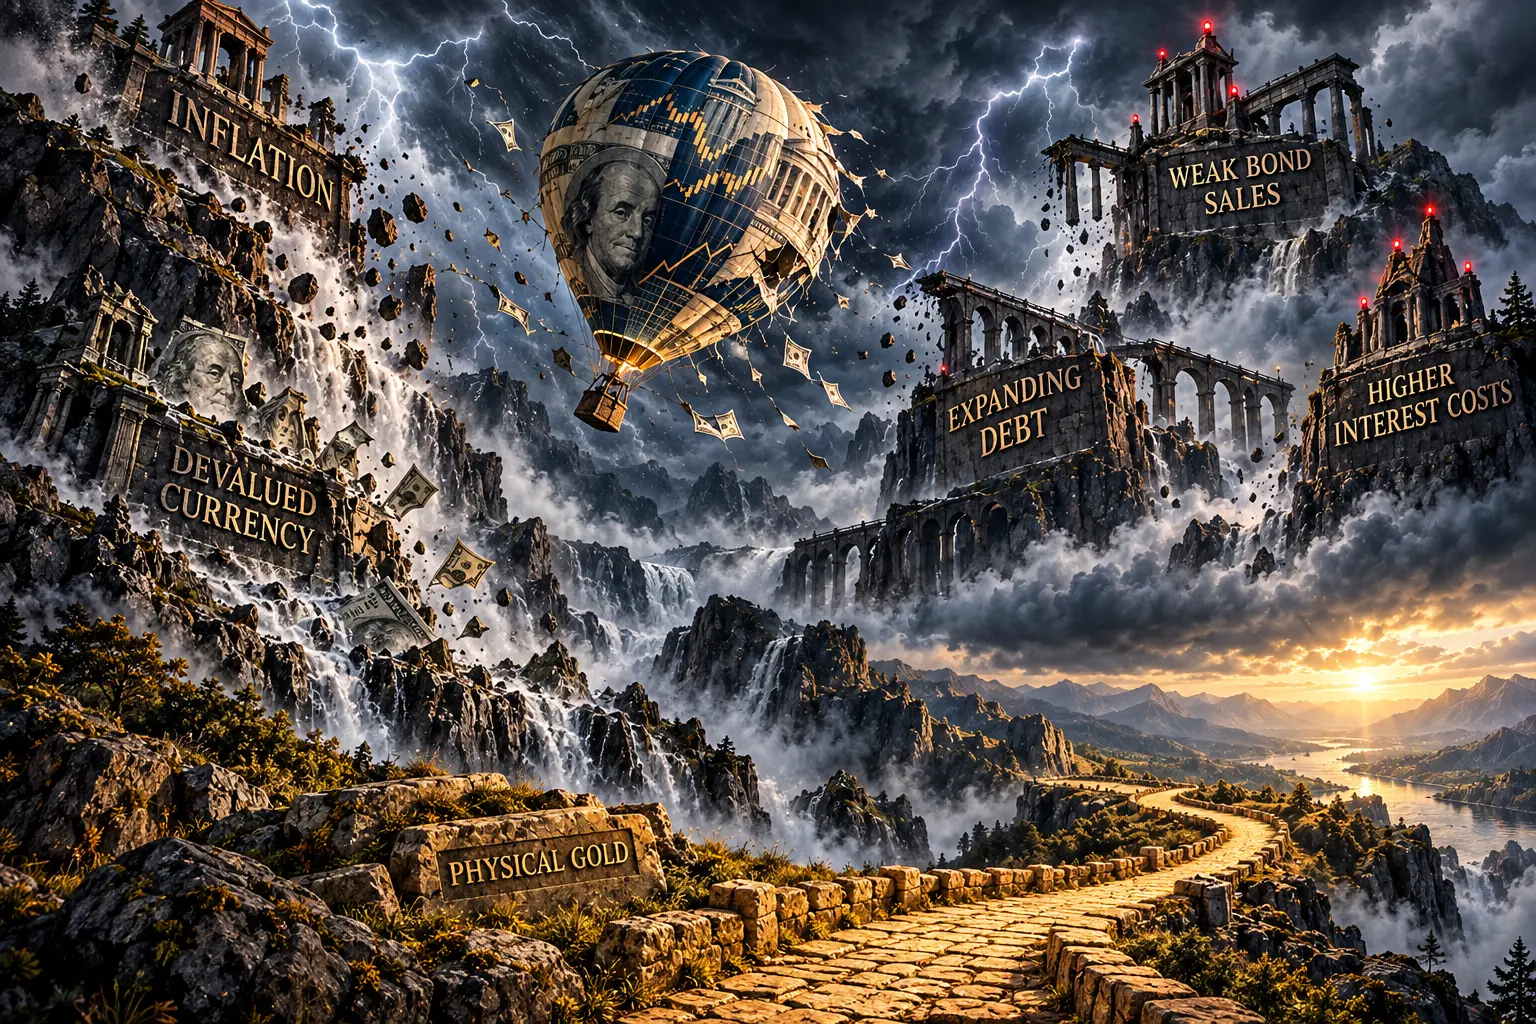
The Less Romantic Path
Physical gold is rarely the most exciting part of a portfolio. It does not announce earnings, launch a new product or promise exponential growth. It does not pay a dividend, and its quoted price can be volatile.
Its appeal is more basic. Properly held physical gold is directly owned. It does not depend upon quarterly earnings, a corporate balance sheet, a fund administrator or another party’s promise to pay. Its purpose is not necessarily to outrun the market balloon during every pleasant ascent. Its purpose is to provide a steadier, independently owned path when the air becomes less cooperative.
Growth and resilience differ
Productive equities may create long-term growth. Physical gold can diversify risks concentrated in financial assets.
Liquidity can change quickly
Market confidence, credit availability and trading liquidity can deteriorate together during periods of stress.
Direct ownership matters
A physical ounce is not a share, debt instrument or claim against an issuer’s balance sheet.
Balance matters more than prediction
The objective is not to forecast the exact date of the next reversal, but to avoid depending upon one favorable outcome.
A Necessary Historical Qualification
It is tempting to say that gold simply soared during the Great Depression. The history is more complicated. The United States was operating under a gold standard, the official price was fixed at $20.67 per ounce, private monetary-gold ownership was restricted in 1933, and the government subsequently revalued gold to $35 per ounce in 1934.
That episode demonstrates the relationship between gold, currency policy and confidence, but it should not be presented as a normal free-market return that every private owner automatically received. The lesson is not that gold must repeat a particular percentage gain. The lesson is that monetary rules themselves can change during severe stress.
Preparing Without Predicting
No one knows when the current market balloon will stop rising, whether it will deflate slowly or whether it will rupture suddenly. Preparation does not require correctly predicting the date. It requires asking the question before the pressure changes:
The purpose of this comparison is not to argue that investors should abandon equities or that physical gold will rise during every market decline. It is to recognize that assets designed primarily for growth and assets held for resilience do not have to perform the same job.
The goal is not to fear the next cycle. It is to build a portfolio capable of surviving it.
Evaluate the Position Before the Pressure Changes
RPMEX maintains a two-way market in physical precious metals. We assist clients who are acquiring, liquidating, exchanging or rebalancing existing holdings. The appropriate decision depends upon objectives, liquidity needs, product premiums and current allocation—not simply today’s market temperature.