When a Stock Market Rally Depends on Cheap Money
A rising index can leave investors overlooking the assumptions holding their portfolios together.
A market does not become sound simply because investors keep bidding it higher. The more important question is what those prices require us to believe about future profits, borrowing costs and the willingness of policymakers to intervene when expectations disappoint.
Our concern is that too much confidence rests on a convenient combination: exceptional future growth, manageable financing costs and a central bank ready to cushion the next serious setback. Each assumption deserves scrutiny. Depending on all three leaves little room for error.
We are not predicting an imminent crash. Our judgment is that a substantial repricing is more likely than a painless resolution if these dependencies persist. That is an assessment of risk, not a statistically established probability or a timetable.
Start with the index itself. The S&P 500 weights companies by their market value, adjusted for shares available to investors. Its largest constituents therefore exert the greatest influence. A strong reading can coexist with weakness among many smaller constituents. That is a feature of the calculation, not proof of manipulation. But it means the headline alone cannot establish how broadly prosperity is being shared.
That distinction matters on Main Street. A household struggling with its grocery bill or the cost of filling its gas tank experiences prosperity differently from an investor whose assets have appreciated enough that those expenses barely register.
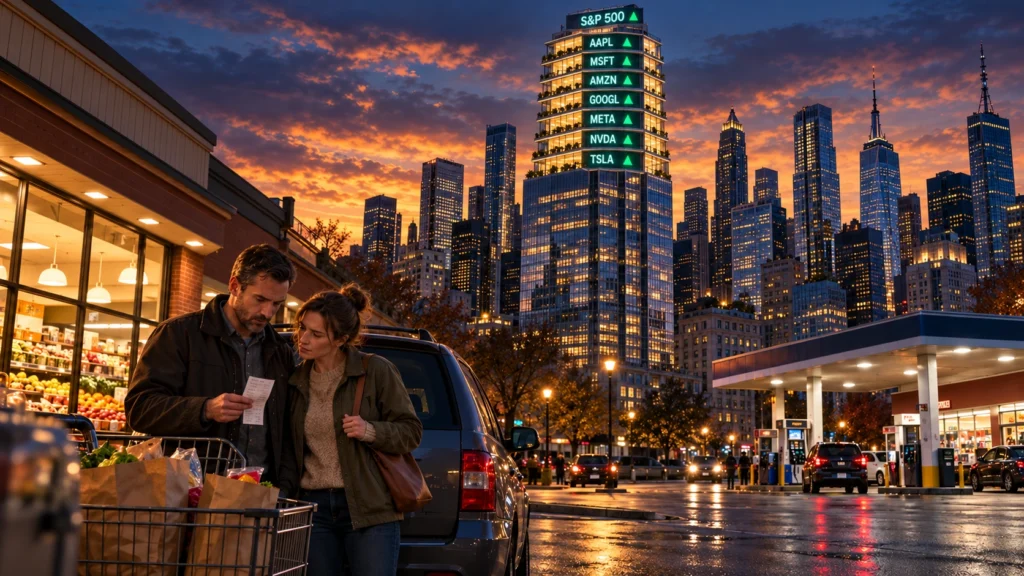
Slower inflation does not, by itself, return prices to earlier levels. Even where particular prices ease, the relevant question for a family is whether its income can comfortably cover its bills. Those who own appreciating assets and have ample financial reserves are better positioned to absorb those pressures. A rising index alone does not show that everyone else is catching up.
This matters to valuations because household spending helps support business revenues. Pressure on household budgets can undermine the growth investors are paying for. A stock market rally is not, on its own, evidence of a broad economic turnaround, and it supplies no solution to the financing pressures beneath it. In our view, confidence in a painless outcome runs ahead of the case made for it.
The next question is what investors are paying for future earnings.
Consider a deliberately simple illustration: a single $100 payment arriving ten years from now is worth about $67.56 today when discounted at 4%. At 6%, it is worth about $55.84. The promised payment has not changed; its present value has fallen roughly 17%.
This is arithmetic, not a forecast for stocks. It shows why the price of capital matters even when the underlying business remains promising.
Artificial intelligence may produce extraordinary economic benefits. That possibility does not establish that every company financing its expansion will earn an adequate return, or that every investor buying its shares will do so at a sensible price. A useful technology and an overpriced investment can exist at the same time.
From our perspective, monetary policy can make that distinction harder to see. When investors expect credit to remain inexpensive or anticipate intervention after serious losses, they may accept prices they would otherwise question. Our concern is that this can postpone adjustment while making the eventual repricing more severe. No single indicator establishes when that adjustment will arrive.
The strongest objection deserves a fair hearing: dominant companies may deserve their valuations. Strong balance sheets, durable earnings and genuine productivity improvements can justify leadership by a relatively small group. Narrow participation can also broaden without a collapse. Anyone claiming that market concentration supplies a reliable crash date is claiming too much.
But what would a durable solution require?
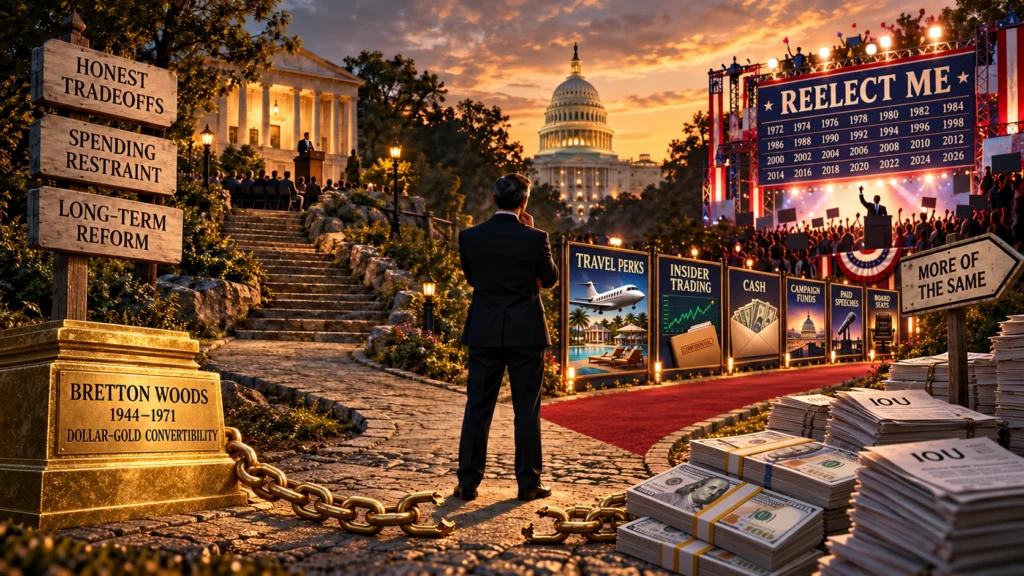
In our view, it would mean bringing government commitments closer to sustainable revenues, allowing borrowing costs to reflect risk, and accepting that some investments cannot be rescued at yesterday’s prices.
Spending restraint, less dependence on cheap credit and recognition of investment losses impose visible costs before their benefits become apparent. Those are difficult political messages to campaign on. Promising relief is easier than explaining who must bear the adjustment.
We do not see a clear, painless path that reconciles those demands with the optimistic assumptions described above. The absence of an easy solution does not tell us when markets will adjust. It does give investors reason to question how much optimism they should pay for.
Investors should also ask whether several apparently different holdings depend on the same favorable outcome. Multiple funds can own overlapping companies. Corporate bonds and equities can both suffer when financing conditions tighten. Diversification deserves examination at the level of economic exposure, beyond the number of account statements.
That is where we see a role for physical precious metals.
Physical gold and silver owned outright and held directly have no counterparty risk. Their value does not depend on an issuer, borrower or financial institution honoring a promise to pay.
Gold does not require a company to meet an earnings forecast or refinance its obligations. Silver also provides tangible ownership, although its industrial uses make it sensitive to economic conditions.
The distinction is direct possession of the metal itself. A claim on metal held by someone else can introduce custody or contractual exposure. Physical ownership still involves price risk, theft or loss, storage and trading costs. No counterparty risk does not mean no risk.
Our position is that financial assets may be priced for more favorable conditions than policymakers can sustainably deliver. If those assumptions remain unresolved, we regard a substantial adjustment as more likely than a painless resolution.
Physical metals can serve a distinct purpose within that preparation. Their rationale should survive even when a market forecast takes longer than expected to unfold.
RPMEX | Ounces of Perspective
Methodology reference: S&P Dow Jones Indices — The S&P 500. Valuation examples are hypothetical calculations. Market outlook and policy conclusions reflect RPMEX’s editorial judgment.